Navigating Tax Residency for Cross-Border Remote Teams
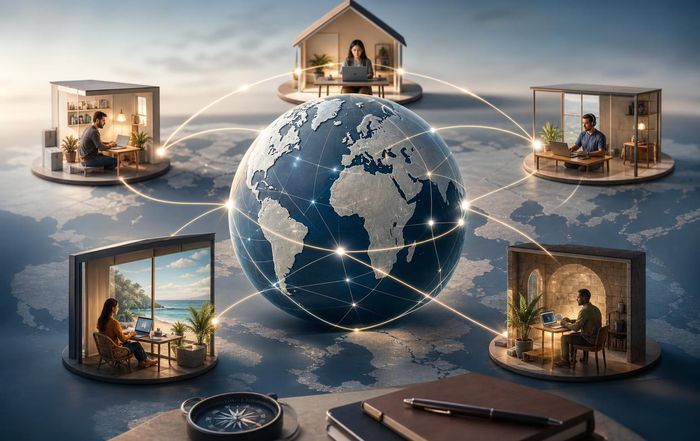
The rise of cross-border remote work has turned a once-clear concept-where someone "lives and works"-into a complex web of tax rules. For companies hiring talent across borders or allowing employees to work from anywhere, tax residency is now a strategic issue, not just a compliance detail. Missteps can trigger unexpected payroll obligations, double taxation, penalties, or even corporate tax exposure in countries where a business has no formal presence. Come and unpack how tax residency works for individuals and companies, why remote work complicates it, and what practical steps leaders can take to manage risks while still benefiting from global talent.
Why tax residency matters more in a remote-first world
Tax residency determines which country has the primary right to tax an individual's worldwide income and, for businesses, where they may be subject to corporate tax. Many countries base residency on days spent in the country, but others also look at where a person's "center of vital interests" lies-family, home, economic ties-or use tests like domicile or habitual abode.
For employers, the stakes are high. If a remote employee's activities in a foreign country are considered significant enough, they can create a permanent establishment (PE), giving that country a right to tax a portion of the company's profits. Guidance from bodies such as the Organisation for Economic Co-operation and Development (OECD) at oecd.org and national tax authorities like the U.S. Internal Revenue Service at irs.gov and HM Revenue & Customs in the UK at gov.uk set the framework, but each jurisdiction applies its own rules and interpretations.
The shift to remote and hybrid work, accelerated by the pandemic and now normalized in sectors like technology, finance, and professional services, has multiplied edge cases. Someone hired in London might work from Spain for half the year; a U.S. engineer might spend months coding from Portugal; a founder might run a startup from a laptop while moving between Asia and Europe. These patterns raise questions not only for personal income tax but also for social security, payroll withholding, and corporate tax exposure.
For readers evaluating cross-border hiring strategies, this intersects with broader questions about employment structures, business expansion, and world trade in services. Understanding tax residency is now part of core operational literacy, not just something outsourced to accountants.
How individual tax residency is usually determined
While each country has its own legislation, several common building blocks appear repeatedly in tax residency rules.
Many jurisdictions use a days-based test, often called a physical presence test. A common threshold is 183 days in a 12-month period, though the exact calculation can vary. For example, the United States applies a "substantial presence test" that looks at days over a three-year window, weighted by year, as described by the IRS at irs.gov. Other countries, such as the United Kingdom, use a more detailed statutory residence test that combines days with ties like housing and family, outlined on gov.uk.
Alongside day counting, many countries consider the center of vital interests-a concept also reflected in OECD model tax conventions. Authorities may ask where someone's permanent home is located, where their family lives, where they hold bank accounts, where they own property, and where they carry out their main economic activities. In some civil law jurisdictions, domicile or habitual residence concepts can be as important as physical presence.
When a person meets residency criteria in more than one country, double tax treaties-bilateral agreements between governments-often provide "tie-breaker" rules. These typically look, in order, at permanent home, center of vital interests, habitual abode, and finally nationality. Tax treaty texts and commentary from organizations like the OECD at oecd.org and reference platforms such as taxfoundation.org or pwc.com can help clarify how these rules are meant to operate, though individual interpretation always rests with local authorities.
For remote workers, the practical implication is that simply "working from the beach" in another country for several months can trigger residency or at least local filing obligations, even if the employment contract and payroll remain tied to the home country. That creates a need for clear policies and guidance from employers, and for individuals to keep careful records of travel and work locations.
Corporate tax residency and permanent establishment risk
Cross-border remote work also affects companies, not just individuals. Corporate tax residency is typically determined by where a company is incorporated, or where its place of effective management is located-that is, where key management and commercial decisions are made. However, even if a company remains tax resident in one country, it can still be taxed elsewhere if it has a permanent establishment in another jurisdiction.
Under the OECD Model Tax Convention, a permanent establishment usually arises when a company has a fixed place of business-such as an office, branch, or factory-or when a dependent agent habitually concludes contracts on its behalf in that country. Tax authorities in major economies, from the European Union (see europa.eu) to Australia at ato.gov.au (via ato.gov.au homepage) and Canada at canada.ca, apply similar concepts with local variations.
Remote work complicates this framework. If a senior executive or key salesperson works permanently from home in another country and negotiates or finalizes contracts there, tax authorities may argue that the home office constitutes a PE. Likewise, if a distributed team performs core value-creating activities (such as R&D or product design) from another jurisdiction, that may increase the risk that a portion of profits should be attributed there.
During the early pandemic, the OECD issued guidance suggesting that temporary dislocations caused by COVID-19 should not generally create new permanent establishments. But as remote work becomes a deliberate, long-term choice, that protective reasoning no longer applies. Companies need to reassess where decisions are made, where contracts are signed, and how they describe roles and authority in employment agreements.
For founders and investors thinking about international expansion or remote-first models, this intersects with broader investment and economics considerations: the tax profile of operations can affect valuation, capital allocation, and where to locate intellectual property.
Employer obligations: payroll, withholding, and social security
Even when a remote worker does not trigger corporate tax residency or a permanent establishment, their physical presence can create payroll and social security obligations for the employer. Many countries require employers with staff working within their borders to register locally, operate payroll, withhold income tax, and contribute to social insurance schemes.
In the European Union, for example, rules coordinated under the EU social security framework (information on europa.eu) typically require workers to be covered by the social security system of one member state at a time. Special forms (such as the A1 certificate) can allow temporary postings while maintaining coverage in the home country, but long-term remote work may shift obligations to the host country. In other jurisdictions, including parts of Asia and Latin America, local employment registration may be required even for a single employee.
For global employers, this creates operational complexity. Some respond by prohibiting employees from working for extended periods in countries where the company has no entity. Others use employer of record (EOR) services, which act as the legal employer in the host country and handle local payroll and compliance. Major EOR and global payroll providers, such as those profiled by Big Four firms like Deloitte at deloitte.com and KPMG at kpmg.com, emphasize the importance of aligning contracts, immigration status, and tax treatment.
This is closely tied to broader employment and finance strategy: payroll structures, benefits, and compliance costs can materially affect unit economics, especially for startups and SMEs scaling remote teams.
Common risk scenarios for cross-border remote teams
While every situation is unique, several recurring patterns create tax residency and compliance risk for employers and workers.
One scenario involves an employee who relocates abroad for personal reasons while keeping their original employment contract. For instance, a software engineer hired in Germany decides to work from Portugal for a year. They may become tax resident in Portugal under local rules, even if German payroll continues. Without coordination, this can result in double taxation, misaligned social security contributions, and penalties for under-withholding.
Another frequent case is the "snowbird" or digital nomad who spends substantial time in multiple countries without establishing a clear primary base. They may inadvertently trigger tax residency in more than one jurisdiction in a single year. Double tax treaties may mitigate double taxation, but only if the individual files correctly and can demonstrate where their center of vital interests lies. Platforms such as OECD at oecd.org and international advisory firms like EY at ey.com or PwC at pwc.com often highlight this as a growing issue in mobility reports.
A third risk arises when senior decision-makers work long-term from a country where the company has no entity. If a chief revenue officer based in the United States moves to Spain and continues to negotiate and sign global contracts from there, Spanish authorities may argue that the company has a PE in Spain and should pay corporate tax on Spanish-attributable profits. Similar arguments can emerge if a head of R&D or product lead directs core business activities from another jurisdiction.
Finally, some companies informally allow "workations" or extended stays abroad without tracking duration or location. Without a centralized approval and tracking process, it becomes difficult to know whether an employee has crossed a residency threshold or created employer obligations. This is where technology-HRIS systems, time-tracking, and policy automation-intersects with tax and legal risk, an area increasingly covered by tech and AI solutions in the global mobility space.
Double tax treaties and relief mechanisms
Double tax treaties are a cornerstone of cross-border tax coordination. They aim to prevent the same income from being taxed twice by two different countries, and they provide mechanisms for resolving residency conflicts. Many treaties follow the OECD Model Tax Convention, while some follow the UN Model, particularly in agreements between developed and developing countries.
These treaties typically address several issues: residency tie-breakers for individuals; definition of permanent establishment for companies; allocation of taxing rights over income categories (employment, business profits, dividends, interest, royalties); and methods of relief (exemption or foreign tax credit). National tax agencies such as the U.S. IRS at irs.gov, Canada Revenue Agency at canada.ca, and HMRC at gov.uk publish treaty texts and guidance.
For remote workers, treaty provisions on employment income are particularly relevant. Many treaties state that employment income is taxable only in the country of residence unless the work is performed in the other country, in which case that country may tax it as well. There are often exceptions for short-term assignments (for example, fewer than 183 days and paid by a non-resident employer with no PE in the host country), but long-term remote work usually falls outside these safe harbors.
Relief mechanisms, such as foreign tax credits, can mitigate double taxation, but they require accurate reporting, documentation of taxes paid abroad, and sometimes complex calculations. For employers, understanding how treaties interact with payroll obligations is essential. Misalignment between where tax is withheld and where liability ultimately lies can cause cash-flow issues and administrative burdens for staff.
Given the complexity, many businesses rely on international tax advisers, including networks like KPMG at kpmg.com and Deloitte at deloitte.com, to design frameworks that align contracts, work locations, and treaty positions. These frameworks increasingly sit alongside broader trade and cross-border services strategies.
Designing a practical framework for cross-border remote work
To navigate tax residency issues effectively, organizations benefit from a structured approach that balances flexibility with control. A starting point is to define clear remote work and travel policies. These typically specify which countries employees may work from, for how long, and under what conditions. Some companies limit unsupervised remote work to jurisdictions where they already have entities or established compliance infrastructure, while others allow broader flexibility but require pre-approval beyond a certain number of days.
Next, employers can implement location tracking and approvals. This does not necessarily mean intrusive surveillance; instead, it can involve self-reporting systems integrated into HR platforms, where employees log planned travel and receive automated guidance on thresholds. When someone proposes a long stay in a new jurisdiction, the system can flag it for review by HR, legal, or tax teams. Increasingly, vendors in the global mobility and HR tech space are using data and AI to automate risk assessment and workflow routing.
A third component is aligning contracts and job descriptions with tax risk. For senior staff working outside the company's home jurisdiction, it may be prudent to limit formal authority to conclude contracts or to ensure that key decision-making remains clearly documented as taking place in the head office. This does not eliminate PE risk, but it can help manage it. Similarly, specifying the "usual place of work" in contracts, and clarifying that cross-border remote work requires approval, creates a stronger governance framework.
Training and communication are also essential. Many employees assume that if their employer permits them to work abroad, all tax implications are handled automatically. In reality, individual tax residency and filing obligations remain personal responsibilities. Providing guidance-through internal resources, webinars, or access to external advisers-can reduce misunderstandings and support compliance.
Finally, companies should periodically review their global footprint. As remote teams grow, what began as a handful of ad hoc arrangements may evolve into a meaningful presence in certain countries. At that point, it may be more efficient to establish a local entity, engage an EOR, or restructure operations. These decisions tie into broader business strategy, markets access, and even sustainable long-term talent planning.
Emerging trends: digital nomad visas and regulatory responses
Governments have not stood still as remote work has expanded. Many countries have introduced digital nomad visas or remote work permits designed to attract location-independent professionals while managing immigration and tax questions. Jurisdictions from parts of Europe and the Caribbean to Asia and Latin America now offer visas that allow stays of 6-24 months, often with specific tax regimes.
In some cases, holders of these visas are exempt from local income tax on foreign-sourced income; in others, they become tax resident and subject to local rules after a certain period. Official information is typically available through national immigration and finance ministries or portals such as europa.eu for EU-related schemes and country-specific government sites accessible via canada.ca, gov.uk, or ato.gov.au. However, these regimes are evolving, and their interaction with home-country tax rules and treaties can be complex.
Tax authorities are also increasing their focus on remote work. Some have issued specific guidance on when home offices may create a permanent establishment, how to treat cross-border teleworkers for payroll purposes, and how to interpret treaty provisions in remote work contexts. Advisory publications from organizations like the OECD at oecd.org and professional bodies such as Chartered Accountants Worldwide at charteredaccountantsworldwide.com provide high-level commentary, but local rulings and practice remain decisive.
For companies, staying abreast of these developments is now part of ongoing compliance, similar to monitoring changes in data protection or employment law. For workers, especially those considering long-term mobility, understanding visa conditions and tax implications is as important as evaluating cost of living or connectivity.
Practical steps for leaders and remote workers
For business leaders overseeing cross-border remote teams, several pragmatic actions can reduce risk while preserving flexibility. First, map where employees are actually working today, including any informal arrangements. This may require surveys, HR data, and travel records. Second, prioritize jurisdictions where multiple staff or key decision-makers are located for deeper review with international tax advisers. Third, implement or update policies that define acceptable remote work patterns, approval processes, and responsibilities for tax and immigration compliance.
Integrating tax considerations into finance and investment planning can also pay dividends. Decisions about where to hire, where to locate intellectual property, and where to establish legal entities all interact with how remote work is organized. In some cases, formalizing operations in a country where many remote staff already reside can reduce uncertainty and support growth.
For individual remote workers, keeping detailed records of travel, work locations, and days spent in each country is essential. Consulting local tax advisers when planning extended stays abroad, especially beyond 90 or 183 days, can help avoid surprises. Reviewing double tax treaties, residency rules, and social security coordination-using official sources like irs.gov, gov.uk, canada.ca, ato.gov.au, and oecd.org-provides a factual foundation, but personalized advice is often necessary where rules intersect.
Cross-border remote work is likely to remain a defining feature of modern employment, especially in sectors covered across technology, world, and business news. Navigating tax residency in this environment is less about finding one-size-fits-all answers and more about building robust frameworks, transparent communication, and adaptable strategies that can evolve as law and practice continue to develop.
