How Inflation Expectations Shape Consumer Confidence - And the Economy
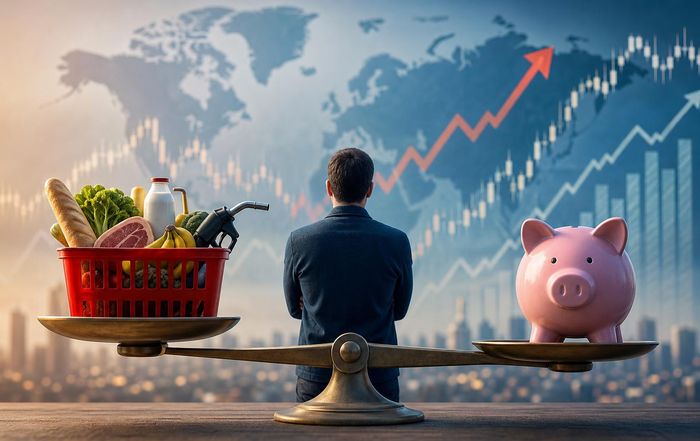
When households think about inflation, they are rarely running models or reading central bank minutes. They are noticing grocery bills, rent renewals, fuel prices, and wage slips. Yet those everyday judgments feed into something economists track closely: inflation expectations. How people expect prices to move over the next year or several years can, in turn, shift how confident they feel about their finances and the broader economy-and that feedback loop can either stabilize or destabilize growth.
This relationship has become especially important after the global inflation spike following the pandemic, Russia's invasion of Ukraine, and energy and supply shocks. Central banks from the U.S. Federal Reserve to the European Central Bank have repeatedly said that keeping inflation expectations "well anchored" is critical. Understanding why helps explain not only recent policy decisions but also how businesses and households might behave in the next downturn or the next boom.
What economists mean by "inflation expectations"
Inflation expectations are simply beliefs about how fast prices will rise in the future. They are usually discussed along three main dimensions.
First, economists distinguish short-term from medium- and long-term expectations. Short-term expectations (often one year ahead) are heavily influenced by visible, volatile prices such as food and fuel. Long-term expectations (five to ten years ahead) are more about trust in institutions like the Federal Reserve or the Bank of England and beliefs about the economy's underlying stability. Central banks and institutions such as the International Monetary Fund and OECD monitor these longer-term expectations closely because they tend to move slowly and reveal whether the public believes inflation will be brought back under control.
Second, expectations can be backward-looking or forward-looking. Backward-looking expectations extrapolate from recent experience: if inflation has been 7% for a year, people may assume it will stay high. Forward-looking expectations incorporate views about policy and the business cycle: if a central bank is aggressively raising interest rates, some households and firms may expect inflation to fall even if it is still high today. Surveys by the University of Michigan, the Bank of England, and the European Commission show that in practice people use a mix of both, with recent price changes having a strong psychological pull.
Third, expectations can be measured in different ways. Policymakers look at household surveys, business surveys, and market-based measures such as inflation-linked bond yields. Each has strengths and weaknesses. Households may overreact to salient items like gasoline, while market measures can be distorted by liquidity or risk premia. Still, taken together, they provide a picture of how the public thinks inflation will evolve-and that picture heavily influences consumer confidence.
Consumer confidence: more than a "mood indicator"
Consumer confidence indices, such as the Conference Board Consumer Confidence Index in the United States or the European Commission's consumer sentiment indicator, are designed to capture how households feel about their current finances and the economic outlook. These measures typically combine questions about current conditions (job prospects, income, ability to make major purchases) with expectations for the next six to twelve months. Because consumer spending accounts for a large share of GDP in many economies, confidence readings are closely watched by investors, central banks, and policymakers.
In practice, consumer confidence reflects three main factors: perceptions of income and employment security, assessments of current price levels and affordability, and expectations about future macroeconomic conditions, including inflation, interest rates, and the risk of recession. When inflation is low and stable, people can plan ahead more easily, and the inflation component fades into the background. When inflation is high or volatile, it moves to the foreground, often dominating household narratives about the economy. That is why, during the post-pandemic inflation surge, confidence measures in many advanced economies dropped sharply even though unemployment remained historically low.
For business readers, this matters because confidence is not just a survey statistic; it is a leading indicator of consumer demand, which in turn drives revenue expectations, investment decisions, and hiring plans. For policymakers, low confidence can amplify downturns: households may cut spending more aggressively than income losses alone would justify if they fear that prices and interest rates will continue to erode their purchasing power.
The key transmission channels: how expectations affect behavior
The link between inflation expectations and consumer confidence operates through several overlapping channels. Understanding these channels helps clarify why similar inflation numbers can have very different effects depending on context and communication.
One central channel is real income expectations. If households expect inflation to outpace wage growth, they anticipate a decline in real purchasing power. Surveys by central banks and institutions like the Bank for International Settlements show that when people believe their real incomes will fall, they become more pessimistic about their ability to save, invest, or make big-ticket purchases such as homes and cars. This pessimism directly lowers consumer confidence, even before any actual income loss occurs. Conversely, if wage growth is perceived as keeping up with or exceeding inflation, expectations of stable or rising real incomes can support confidence even in a higher-inflation environment.
Another channel runs through interest rates and borrowing conditions. Households understand-at least in broad terms-that central banks respond to high inflation with higher policy rates, which tend to raise mortgage rates, credit card costs, and loan repayments. When people expect inflation to remain elevated, they often also expect tighter monetary policy and more expensive credit. This anticipation can weigh on confidence, particularly in economies where variable-rate mortgages or high household debt levels make consumers sensitive to rate changes. For fans following finance and monetary policy, this interaction between inflation expectations, rate expectations, and sentiment is a key driver of market volatility.
A third mechanism is precautionary behavior. If households expect prices to keep rising rapidly, they may bring forward purchases-buying durable goods today rather than next year when they think they will be more expensive. In the short run, this can boost spending, but it is often accompanied by anxiety and a sense that the current environment is unsustainable. Over time, as budgets become strained, the same expectations can lead to defensive cuts in discretionary spending, further depressing confidence. This dynamic has been observed repeatedly in high-inflation episodes documented by the IMF and World Bank across both advanced and emerging economies.
Finally, there is a psychological and narrative channel. Inflation is highly salient because it touches daily life. Media coverage, political debate, and social conversations can reinforce perceptions that "everything is getting more expensive" or that "the central bank has lost control." Behavioral research by institutions like the OECD and major universities suggests that negative narratives about inflation can reduce confidence even when objective measures of real income or employment have not yet deteriorated. In other words, expectations and stories can move ahead of fundamentals.
Anchored vs. unanchored expectations: why central banks care
Central banks repeatedly emphasize the importance of keeping inflation expectations "anchored," particularly over the medium to long term. An anchored expectation means that, despite short-term fluctuations in actual inflation, households and businesses broadly believe that inflation will return to the central bank's target (often around 2%) over time. An unanchored expectation means that people start to doubt the central bank's commitment or ability to control inflation, leading them to anticipate persistently higher or more volatile price increases.
When expectations are anchored, inflation shocks-such as an energy price spike-tend to have temporary effects on confidence. Consumers may become more cautious, but they generally believe that real incomes will stabilize as inflation falls back. Wage demands and price-setting behavior remain relatively moderate, reducing the risk that a one-off shock turns into a self-reinforcing spiral. In this environment, central banks like the European Central Bank or the Bank of England can often tighten policy more gradually, and consumer confidence tends to recover more quickly once headline inflation declines.
By contrast, when expectations become unanchored, the feedback loop between expectations, behavior, and actual inflation can intensify. Households may assume that high inflation is the "new normal" and demand larger wage increases; firms, anticipating higher costs, may raise prices more aggressively; and savers may shift out of cash into assets they believe will protect them from inflation. Historical episodes studied by the Bank for International Settlements show that such dynamics can make inflation more persistent and volatile, requiring more forceful and prolonged monetary tightening to restore credibility. During these periods, consumer confidence often remains depressed even as unemployment rises, because households fear both job loss and continuing price instability.
This is why central banks invest heavily in communication strategies, forward guidance, and transparency. Clear explanations of policy decisions, inflation forecasts, and risk assessments aim to shape expectations directly. For example, when the Federal Reserve or the ECB signals that it will keep interest rates "higher for longer" until inflation is back near target, it is not only managing financial markets; it is also trying to convince households and firms that inflation will be contained, thereby supporting more stable confidence over the medium term.
Evidence from recent inflation shocks
The inflation surge that began in 2021 offered a real-time test of how inflation expectations influence consumer confidence across different economies. In the United States, headline inflation peaked above 9% in mid-2022, the highest rate in four decades. Consumer sentiment, as measured by the University of Michigan, fell to record lows, even as unemployment remained near historic lows. Survey data showed that short-term inflation expectations spiked sharply, driven by fuel and food prices, while longer-term expectations moved up more moderately but remained within a range consistent with the Federal Reserve's target.
As inflation started to fall in 2023 and 2024, short-term expectations declined, and consumer confidence partially recovered, but many households still reported feeling financially squeezed. Analysts at organizations such as the Brookings Institution and major banks noted that cumulative price increases-rather than the current inflation rate alone-were weighing on perceptions. This illustrates an important nuance: even if expectations about future inflation improve, past price jumps can leave a lasting imprint on confidence, particularly among lower-income households that have little buffer.
In the euro area and the United Kingdom, a similar pattern emerged but with some differences. Energy price shocks linked to the war in Ukraine and structural issues in gas markets pushed European inflation higher and kept it elevated for longer in some countries. The European Commission's consumer sentiment indicators showed deep pessimism in several member states, with inflation cited as a leading concern. The Bank of England faced especially difficult trade-offs as both inflation and mortgage rates rose, eroding real incomes and pushing confidence down. Yet surveys by the ECB suggested that long-term inflation expectations remained closer to target than in some past episodes, supporting the view that institutional credibility helped prevent a full-scale de-anchoring.
Emerging markets present a different, more varied picture. In some economies with a history of high or volatile inflation, such as parts of Latin America, households have long expected elevated inflation and may be more accustomed to coping mechanisms like dollarization or frequent price renegotiation. In others, including some Asian economies that had enjoyed long periods of low inflation, the recent shock came as a surprise and had a stronger effect on confidence. Data compiled by the IMF and World Bank suggest that where central banks had established strong anti-inflation reputations, consumer confidence, though dented, recovered more quickly once headline inflation started to fall.
Distributional effects: why expectations hit some households harder
Inflation expectations and their impact on confidence are not uniform across the population. Income level, age, debt profile, and asset ownership all shape how people perceive and respond to expected price changes. For businesses and policymakers, understanding these differences is essential for anticipating shifts in consumption patterns and political pressures.
Lower-income households typically spend a larger share of their income on necessities such as food, energy, and rent. Because these categories are often more volatile and have risen sharply in recent years, their inflation experience and expectations can be significantly worse than aggregate figures suggest. Surveys by central banks and institutions like the OECD indicate that lower-income respondents tend to report higher expected inflation and greater concern about making ends meet, leading to steeper declines in confidence. This can translate into sharper cutbacks in discretionary spending-an important consideration for sectors such as retail, travel, and hospitality, covered in more detail in our well researched business and travel pages.
Age and life stage also matter. Younger households, especially those trying to enter the housing market, may see high inflation combined with rising interest rates as a double blow: higher prices for homes and higher borrowing costs. Their expectations about long-term affordability can deteriorate, weighing on confidence even if their current employment prospects are solid. Older households on fixed incomes may be particularly sensitive to inflation eroding the real value of pensions and savings, though those with substantial financial or real-asset holdings can sometimes benefit if asset prices rise with inflation.
Debt and asset positions create further divergence. Highly leveraged households, especially with variable-rate mortgages, may see expected inflation as a warning sign that interest rates will remain high, reducing confidence. By contrast, households with fixed-rate debt and substantial real assets might view moderate inflation as less threatening, or even mildly beneficial, because it erodes the real value of their liabilities. Such differences help explain why consumer confidence can move differently across regions or demographic groups even within the same country.
Business implications: pricing, wages, and strategic planning
For companies, inflation expectations and consumer confidence are not abstract macro indicators; they are inputs into concrete decisions about pricing, wages, inventory, and investment. Firms that misread household expectations can find themselves either leaving money on the table or alienating customers and employees.
On the pricing side, when consumers expect higher inflation, they may tolerate more frequent or larger price increases-up to a point. However, if confidence is low and real incomes are under pressure, demand becomes more price-sensitive. Businesses in consumer-facing sectors must balance the need to pass on higher input costs with the risk of volume losses. Monitoring both inflation expectations and confidence surveys can help calibrate this balance. For example, companies might choose to adjust product sizes, offer more promotions, or introduce lower-priced lines when surveys show deteriorating confidence, a trend our markets and retail coverage frequently highlights.
Wage negotiations are another critical area. When workers expect high inflation, they are more likely to demand larger nominal wage increases to protect real incomes. If businesses also expect inflation to stay high, they may be more willing to grant such increases, potentially embedding higher inflation into cost structures. However, if management believes central banks will succeed in bringing inflation down quickly, they may resist locking in high wage growth. This tension can affect labor relations, turnover, and productivity. Understanding how both employees and managers perceive future inflation is therefore central to HR and compensation strategy, closely related to topics covered in our employment section.
Strategically, firms with long investment horizons must consider how persistent shifts in inflation expectations could alter demand patterns, financing costs, and valuation metrics. For investors and corporate finance teams, scenarios around inflation and consumer confidence feed into decisions about capital structure, dividend policy, and risk management. Coverage in our updated investment and economics pages often explores how these macro expectations translate into sector-level opportunities and risks.
Policy responses: stabilizing expectations and supporting confidence
Policymakers have three broad levers to manage the interplay between inflation expectations and consumer confidence: monetary policy, fiscal policy, and communication. Each carries trade-offs, and their effectiveness depends heavily on credibility and institutional design.
Monetary policy, led by central banks like the Federal Reserve, European Central Bank, and Bank of England, is the primary tool for controlling inflation over the medium term. By raising or lowering policy interest rates and adjusting balance sheets, central banks influence borrowing costs, financial conditions, and ultimately aggregate demand. When inflation expectations rise, central banks may tighten policy more aggressively to signal their determination to restore price stability, even at the risk of slowing growth. This can initially dampen consumer confidence by raising borrowing costs and raising fears of recession, but if successful it helps re-anchor expectations and support confidence over the longer run.
Fiscal policy-government decisions on taxes, spending, and transfers-can cushion the impact of inflation on real incomes, particularly for vulnerable groups. Targeted energy subsidies, temporary tax cuts, or direct cash transfers can help maintain consumption and confidence during price spikes. However, if fiscal support is perceived as excessive or poorly targeted, it can fuel concerns about future inflation or public debt sustainability, undermining the very expectations policymakers are trying to stabilize. Institutions such as the IMF and World Bank have emphasized the importance of well-designed, time-limited measures that protect the vulnerable without overstimulating demand.
Communication is the third, often underestimated, pillar. Clear, transparent messaging about inflation drivers, policy responses, and expected trajectories can shape expectations directly. Central banks increasingly publish detailed forecasts, scenario analyses, and meeting minutes to explain their thinking. Governments may also engage in public information campaigns to contextualize price shocks-for example, explaining the role of global energy markets or supply chain disruptions. When communication is consistent and credible, it can prevent worst-case narratives from taking hold, supporting both inflation expectations and consumer confidence. When it is inconsistent or politicized, it can do the opposite.
Technology, data, and the future of expectations
Advances in data collection, AI, and digital platforms are changing how inflation expectations and consumer confidence are formed and measured. Central banks and research institutions now analyze real-time price data, online search behavior, and social media sentiment to complement traditional surveys. Companies such as Google and other big tech platforms provide anonymized trend data that can serve as early indicators of shifting concerns about inflation, jobs, or economic prospects.
At the same time, the information environment in which households form expectations has become more fragmented and rapid. News about inflation, rate decisions, or currency moves spreads instantly through social networks and messaging apps, sometimes amplifying extreme views or misinformation. This can make expectations more volatile and more sensitive to headlines, complicating the task of policymakers and businesses alike. Coverage in our new tech and AI sections often explores how digital tools can both help and hinder economic decision-making.
For investors, entrepreneurs, and executives, this evolving landscape means that traditional macro indicators are necessary but not sufficient. Combining official inflation and confidence data with high-frequency, alternative indicators can provide a more nuanced view of how households are likely to behave. It also underscores the value of clear, consistent corporate communication about pricing, wages, and strategy, to help anchor expectations among customers, employees, and shareholders.
Why this relationship will stay central to the economic story
Inflation expectations and consumer confidence sit at a critical junction between macroeconomic policy and everyday financial decisions. When expectations are stable and confidence is reasonably strong, economies can absorb shocks more smoothly, and businesses can plan with greater clarity. When expectations become unanchored and confidence collapses, even modest shocks can trigger outsized reactions in spending, investment, and political pressure.
For those smart people focused on business, finance or tracking both indicators-and understanding the mechanisms that connect them-offers valuable insight into future demand, interest rate paths, and market volatility. As central banks continue to navigate the post-pandemic environment, and as new shocks inevitably emerge, the tug-of-war between what people expect prices to do and how confident they feel about their financial future will remain one of the defining dynamics of the global economy.
